EDITOR’S NOTE:&& nbsp In the Fall of 2021, a group of trainees at Wake Forest University participated in a class on Data-Driven Advocacy. Their goal was to discover a concern that was broadly pertinent to inequality, response that question utilizing standard tools of information science, and convincingly interact that response plainly to a broad audience in a collaboration with the Puffin Nation Fund Writing Fellowships. This post is the very first of the end products that came out of that course. The authors looked for to comprehend whether own a home provided monetary stability throughout times of financial challenge, such as the current Covid pandemic. As you will see, the response is more complex than the mythos of the American Dream.
Owning a house stays a crucial part of accomplishing the American dream. Individuals in the United States are taught to think that homeownership signifies success, and this dream has to do with more than individual satisfaction. Property owners typically take pleasure in considerable financial advantages like tax breaks for home mortgage payments, capital gains exemptions, aids, and other monetary tools that are not readily available to those who lease their houses. House equity credit likewise permits house owners to make use of the worth of their residential or commercial property for liquidity in times of crisis, such as a health emergency situation or joblessness.
While there are support programs for tenants– like the Section 8 real estate program– they are pestered by long waiting lists and little accessibility. Just one in 4 homes in the United States that gets approved for such help in fact gets it. According to the Federal Reserve Bank, the normal house owner had a net worth of $255,000 in 2019, compared to a simple $6,300 amongst occupants.
The severe monetary battles produced by the Covid pandemic used a look at how these distinctions can play out. According to the Bureau of Labor Statistics, joblessness increased from 3.5 percent in February 2020 to 14.7 percent in April2020 House owners made extensive usage of their benefits throughout this time. A research study from The Wall Street Journal discovered that American families conserved $5.3 billion by re-financing from January to October of 2020.
But just how much did these securities assist property owners throughout the pandemic? Were they more economically protected than tenants? Utilizing information from the Household Pulse Survey carried out by the United States Census Bureau, we had the ability to compare both groups’ monetary self-confidence. The HPS has actually been gathered bimonthly given that April 2020 and determines the impact of Covid on work status, food security, and real estate security on specific homes.
Because earnings and homeownership are associated, we arranged participants who stated that they were either “extremely positive” or “reasonably positive” that they would have the ability to pay their next lease or home loan payment on time into brackets of low-income (less than $50,000 each year in home earnings), middle-income ($50,000 to $150,000), and high-income (more than $150,000) prior to comparing them. 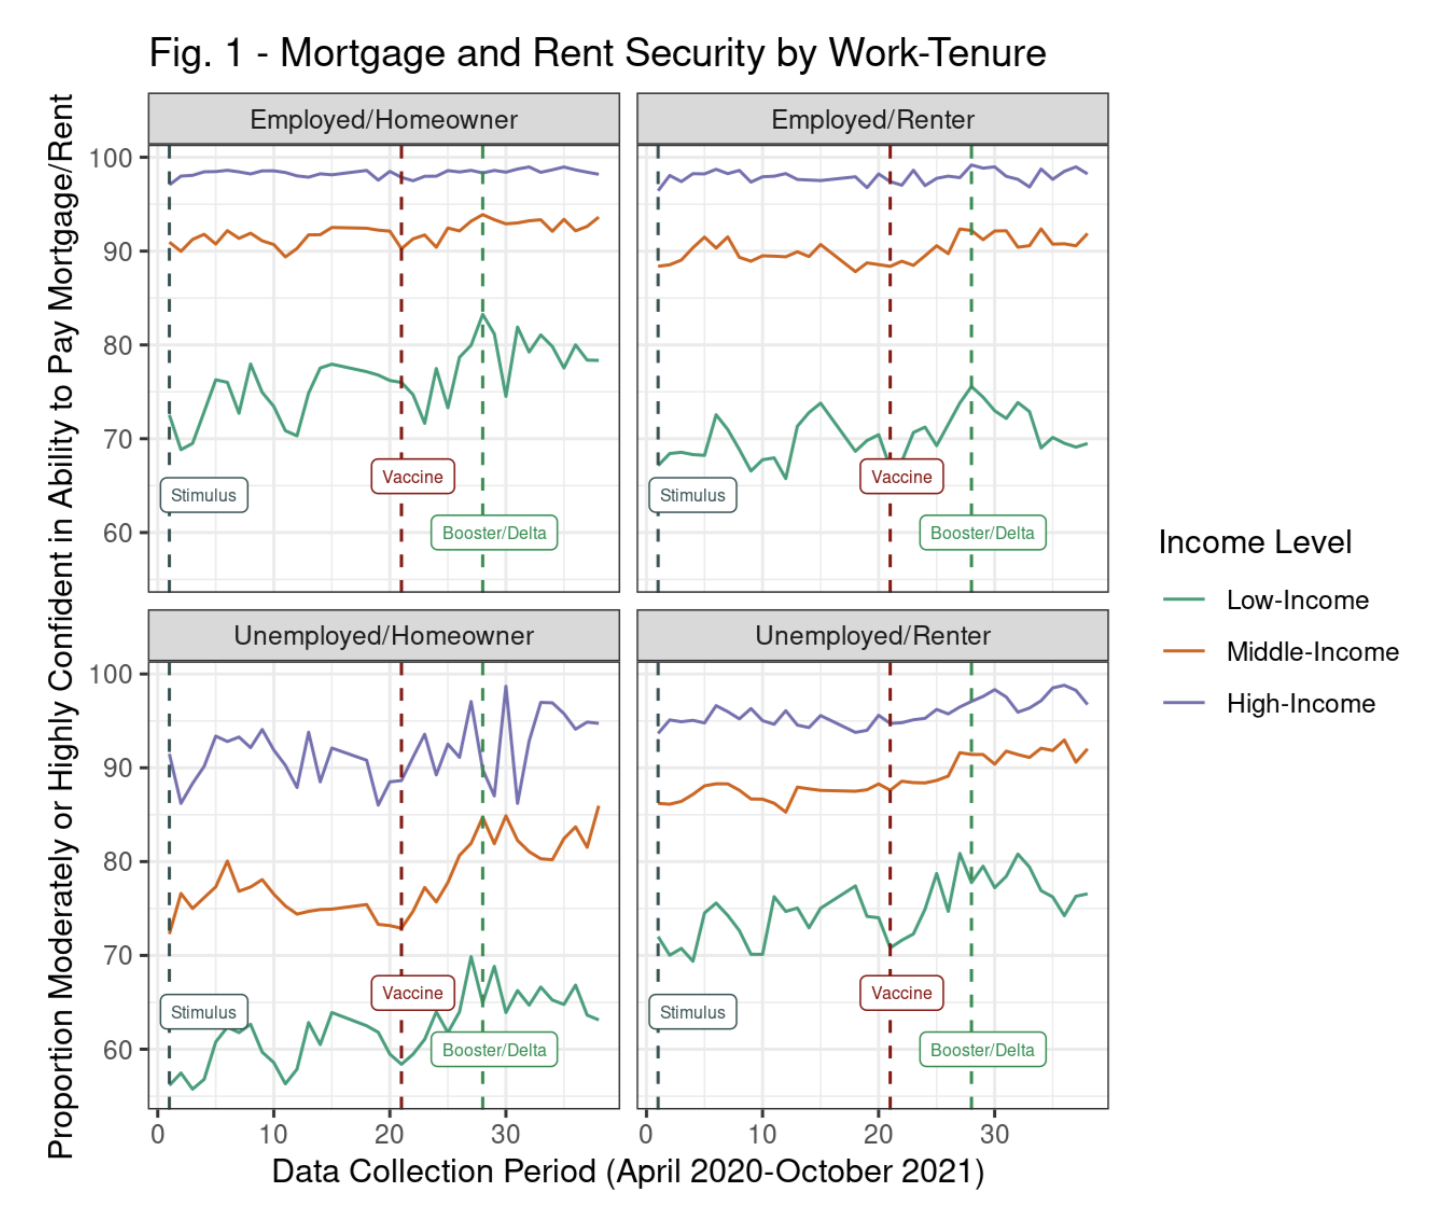
The x-axis of Figure 1 reveals the time frame in which information was tape-recorded, numbered by the biweekly collections. Duration 10 represents the 20 th and 21 st week after collection began on April 23,2020 We likewise included vertical lines at crucial turning points throughout the pandemic: the very first stimulus check being sent to certifying families after the finalizing of the CARES Act (mid-April 2020), the very first vaccines being presented (December 2020), and discussions about the booster shot in addition to worry focused around the Delta variation in the United States (August 2021). The y-axis reveals the percentage of individuals who reported sensation reasonably or extremely positive that they might pay their lease or home mortgage throughout the particular two-week duration.
Surprisingly, the information reveals that jobless house owners had the most affordable monetary self-confidence levels of any group, no matter earnings level. Their self-confidence was likewise extremely variable week-to-week, even amongst the greater earnings groups. This opposes the typical expectation that homeownership instantly results in more monetary stability.
On the other hand, used participants who owned a house had regularly greater monetary self-confidence than occupants had with equivalent earnings. Hence, while homeownership can undoubtedly increase monetary stability, home mortgages can trigger much more of a monetary problem if the owner is not gotten ready for a duration of joblessness.
Figure 2 reveals monetary self-confidence amongst low-income participants (those with less than $50,000 annually in family earnings) by self-identified racial group. Utilized house owners in any group were generally more positive than used occupants in the exact same group; jobless property owners were less positive than jobless tenants. This was not real amongst Asian participants at the start of the pandemic, when house owners were similarly or less positive than occupants, however had actually ended up being real by the end of the pandemic. Possibly unsurprisingly, non-white racial groups had lower monetary self-confidence no matter their work-tenure status.
It is essential to keep in mind that for utilized participants, monetary security amongst non-white property owners was qualitatively comparable to monetary security amongst white tenants and considerably higher than that for non-white tenants. For this factor, it appears that homeownership partly offsets monetary drawbacks that are associated with race amongst the utilized.
On the other hand, out of work non-white house owners are the least economically positive group in general. Hence, home mortgages can likewise be an out of proportion concern for racial minority groups in especially hard scenarios.
The pandemic has actually interfered with most elements of American life, however it has actually not impacted all groups similarly. Homeownership can be exceptionally advantageous and assist create multi-generational wealth, however it does not appear to be an automated course to monetary self-confidence. Owning a house and being used is typically viewed as a sign that somebody is solvent and effective, however our outcomes bring into question how we usually think of monetary stability.
Perhaps some property owners were uninformed of alternatives and tools that might have increased their monetary security, such as house equity credit lines and refinancing, or were unpleasant pursuing them. According to the Federal Home Loan Mortgage Corporation (Freddie Mac), “although a greater percentage of Black and Hispanic debtors have a monetary reward to re-finance, they re-finance their home mortgages at significantly lower levels than White customers.” Those looking for to purchase a house– and those motivating them to do so– must make sure that their purchase will be a monetary property rather of a liability throughout times of monetary difficulty and organizations must guarantee that they are serving the groups that require it most by supplying sufficient details and access to credit and capital on a genuinely equivalent basis.
Comments
Post a Comment